

CreditWise from Capital One

- 40.63K Reviews
- 4.6
- Downloads
- 5,000,000+
Our take on CreditWise from Capital One from Appgk
CreditWise from Capital One is the kind of finance app that makes a strong first impression because it turns an otherwise vague worry—“What is happening with my credit?”—into something I can check quickly. I found it most useful as a simple monitoring companion rather than a complete financial command center. It is free, aimed at everyone, and developed by Capital One Services, LLC, so the appeal is easy to understand: open the app, look at your credit picture, and get a clearer sense of whether anything needs attention.
After using it beyond the initial curiosity, my opinion became more specific. The real question is not whether a free credit app is handy during the first week. It is whether I still have a reason to open it after the novelty fades. CreditWise earns that place for people who want a low-effort way to stay aware of changes, but it is less compelling for anyone expecting detailed budgeting, full credit-report research, or a replacement for their bank’s everyday money tools.
What makes the first week appealing
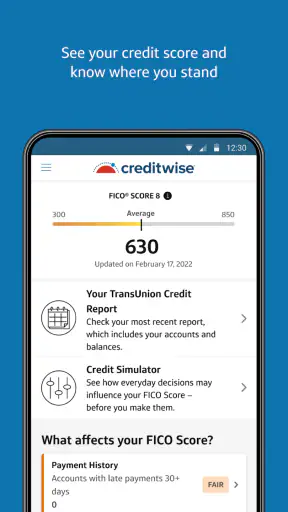
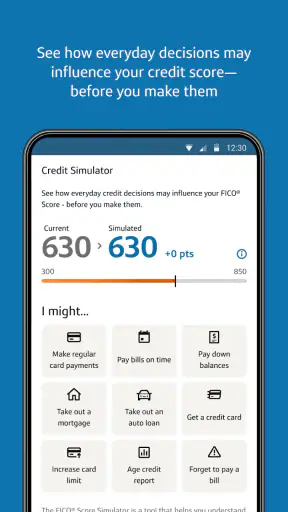
The first useful step is simply seeing credit information in one focused place. Many people know that credit matters but do not know how often to check it or what kind of change deserves attention. CreditWise lowers that barrier. Its store summary centers on a free credit score and monitoring, and that narrow purpose is a strength when I do not want to sort through a crowded banking app to find the information.
I also like the psychological effect of a quick check. Instead of waiting until I am applying for an apartment, changing insurance, or considering a loan, I can build awareness earlier. That does not magically improve a credit profile, but it helps turn credit from an occasional emergency topic into something I can observe over time. For a first-time credit user, that shift can be more valuable than a long list of advanced financial tools.
Best Parts of CreditWise from Capital One
Things to Keep in Mind About CreditWise from Capital One
The app has a 4.6 average from around 116 thousand ratings, and its audience is substantial, with over 5 million installs. Those figures do not prove that every user will enjoy it, but they do show that the basic idea has broad appeal. I can see why: a dedicated credit app feels less intimidating than opening a full financial dashboard packed with balances, transfers, offers, and spending categories.
One practical use case is preparing for a major application without obsessively checking every day. I might open CreditWise before comparing rental options, review whether the information looks familiar, and make a note of anything unexpected. If I see a change I do not recognize, the important next step is investigation rather than panic. The app can prompt awareness, but I still need to understand the underlying account or report and contact the appropriate institution when something looks wrong.
News and Features Related to CreditWise from Capital One

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
That distinction matters. A credit score is a useful signal, not a complete explanation of financial health. A high number does not mean that a loan is affordable, and a lower number does not explain every reason an application may be treated differently. I appreciate CreditWise more when I treat it as an early-warning and education tool instead of a promise of approval.
Useful for building a checking habit
During the first week, I would not try to memorize every detail. I would establish a baseline, look through the main monitoring information, and decide what kind of changes would make me investigate further. That approach avoids one of the common mistakes with credit apps: repeatedly refreshing without knowing what action a change should trigger.
Don't want to read the full review?
For someone who has never monitored credit, the app is especially approachable because it does not require paying for a subscription to begin. The price is free, and the content rating is Everyone, which fits its broad, non-specialist purpose. I would recommend starting with a single weekly or monthly reminder rather than turning the app into a source of daily anxiety.
There is also a useful trade-off in its simplicity. A focused credit view is easier to understand, but it cannot replace a full personal-finance system. If I want detailed spending categories, bill scheduling, savings targets, investment tracking, or a consolidated view of several financial institutions, I would look to a banking app or a dedicated budgeting service instead. CreditWise works best beside those tools, not necessarily instead of them.
Screenshots
Does it keep earning attention month after month?
The lasting value comes from monitoring, not novelty. Credit information is easy to ignore when everything appears normal, yet that is exactly when occasional checks are most useful. A recurring glance can help me notice a change sooner than I would if I only thought about credit when applying for something important.
I found the strongest long-term workflow to be deliberately boring: check at a consistent interval, compare the current picture with what I remember, and take action only when there is a meaningful reason. That keeps the app from becoming a compulsive score-refreshing tool. It also makes the information easier to interpret because I am looking for movement and context rather than reacting emotionally to every small variation.
Another non-obvious benefit is that monitoring can improve the quality of questions I ask elsewhere. If I am discussing a credit-card account, a loan, or a possible reporting issue, knowing when I noticed a change gives me a clearer starting point. I can record the date of a surprising movement in my own notes and then review statements or contact the relevant provider. CreditWise does not do all that investigation for me, but it can help me notice when investigation is warranted.
This makes it useful for people rebuilding financial routines. Someone who recently started paying closer attention to bills may not need a complicated dashboard; they may simply need a visible reason to keep credit on the monthly checklist. In that role, the app provides recurring value through awareness. The benefit is quiet and cumulative rather than dramatic.
I would still avoid treating the displayed score as an exact forecast of every lender’s decision. Different lenders can use different information and evaluation methods, and credit data can change as accounts update. The sensible habit is to use the app to observe trends and identify questions, not to assume that one number guarantees a particular outcome.
Where it fits beside other financial apps
Compared with a bank app, CreditWise is more focused. A bank app is usually the better place to move money, inspect transactions, manage accounts, or handle payments. Compared with a budgeting app, CreditWise is not designed to show me where my household spending is going or whether I am meeting savings goals. Compared with a credit-report service that offers a broader research experience, its appeal is the lighter, more approachable monitoring routine.
That makes the choice fairly straightforward. I would choose CreditWise when my main need is a free, dedicated view of credit awareness. I would choose a budgeting tool when my problem is spending control. I would use a bank’s own app when I need account actions. Someone who wants deep credit education, extensive report analysis, or a broad collection of financial services may find a more specialized alternative better suited to that purpose.
The app’s audience size also gives it a reassuring sense of maturity. It has around 41 thousand written reviews, and the current version is 1.150.0. I do not see those details as a reason to install anything automatically, but they suggest this is an established product rather than a temporary experiment. For a finance app, that matters because I want a tool that fits into a stable routine instead of one I may abandon after a brief trial.
The maintenance burden is low, but not zero
CreditWise is easy to maintain if I give it a limited job. I would keep notifications purposeful, open it on a schedule that matches my financial life, and avoid checking simply because I feel nervous. The app itself may require little effort, but interpreting financial information still requires judgment. No monitoring service can decide whether a change is harmless, urgent, or caused by an account I forgot about.
That is the main maintenance task: connecting what I see in the app to real-world records. If a credit change appears, I may need to check statements, remember recent applications, review account activity, or contact a provider. The app can shorten the time between a change and my awareness of it, but it cannot remove the responsibility of confirming what happened.
I would also keep the app updated through the normal store process. It was released on April 12, 2016, and its current version is listed as 1.150.0, showing a product that has continued through multiple iterations. It requires iOS 11 or later, so users on very old Apple devices should check compatibility before planning around it. That requirement is not demanding for most modern devices, but it is still worth considering if an older phone is part of the household.
One practical tip is to decide in advance what counts as an action trigger. For me, that might be an unfamiliar account-related change or information that does not match my recent activity. Without that rule, monitoring can become passive scrolling. With it, each check has a purpose: either everything looks familiar and I move on, or I have a specific question to investigate.
Another useful habit is separating credit monitoring from credit improvement. Monitoring tells me what may have changed; improvement usually depends on broader behavior such as paying obligations responsibly and managing applications carefully. I would not install this app expecting it to repair a financial situation by itself. I would install it to make the situation easier to observe.
What may cause fatigue over time
The biggest source of fatigue is repetition. Once I have learned where the important information appears, the app may feel uneventful during long stretches when nothing changes. That is not necessarily a weakness in monitoring, but it can make a user wonder whether the app deserves space on the phone. Its value depends on accepting that prevention and awareness often look boring.
There is also a risk of over-focusing on the score. A visible number can become the center of attention even when the more important question is whether the underlying accounts and activity are familiar. I prefer to look for context and trends rather than celebrate or worry about every movement. If seeing the score repeatedly increases stress without leading to useful action, a less frequent schedule may be healthier.
CreditWise may also feel limited to users who want one app to manage every part of their finances. The focused design that helps beginners can frustrate experienced users who expect in-depth planning tools. I would skip it as a primary finance app if my daily needs revolve around cash flow, bills, investments, joint account management, or detailed household reporting.
There is a second trade-off for people who already use several financial services. Adding another app can create more notifications, more logins, and another place to check. The best reason to keep CreditWise is not that it covers everything, but that its credit-monitoring role is distinct enough to justify the extra space. If another trusted service already provides the exact monitoring routine I need, the added benefit may be modest.
Privacy and trust also deserve personal consideration with any finance app. I would read the current permissions and privacy information in the app store and make sure I understand what I am comfortable sharing before setting it up. The fact that Capital One Services, LLC is the developer may be reassuring to some users and irrelevant to others, but the decision should still be based on the complete current terms, not just the name on the app.
Finally, I would not confuse a free price with a cost-free experience. There may be no purchase required to start, but my time and attention still have value. If the app encourages me to check constantly, it is costing more attention than the information is worth. Used with a clear schedule, that problem is much less likely.
Who should keep it installed?
I think CreditWise is a good fit for someone who wants a straightforward entry point into credit monitoring, especially a person who has never made checking credit part of a routine. It is also useful before a planned financial milestone, when I want a simple way to notice anything unfamiliar rather than discovering a problem at the last minute.
It can suit users who already have a bank app and budgeting system but lack a dedicated, low-friction credit check. In that setup, each tool has a clear role: the bank handles transactions, the budget handles spending decisions, and CreditWise handles credit awareness. That separation is more practical than expecting one app to provide a perfect view of every financial concern.
I would be more cautious recommending it to someone who becomes anxious about numerical changes or who expects exact predictions about approvals. I would also point experienced financial planners toward more specialized tools if they need extensive analysis. The app is deliberately approachable, and that means it may not satisfy someone who wants every detail in one place.
For a realistic monthly scenario, imagine that I am considering a move and may need to apply for housing. I open the app as part of preparation, review the information for anything unfamiliar, and write down questions rather than assuming the displayed score guarantees acceptance. If nothing looks unusual, I continue with the application process and retain the app as a periodic check. If something does look unfamiliar, I investigate before treating it as a simple score fluctuation. That is a useful workflow because it turns monitoring into preparation, not superstition.
For another scenario, a new credit user could check after establishing a financial routine, learn what the normal view looks like, and then return at a consistent interval. The app becomes a quiet checkpoint. It does not replace responsible account management, but it can make neglect less likely.
My long-term verdict
After the first-week appeal wears off, CreditWise remains worthwhile when I give it a modest, specific job: help me stay aware of my credit without charging me for the basic monitoring experience. Its free price, accessible focus, Everyone rating, and established presence make it easy to recommend as a starting point.
The lasting value is the habit, not the excitement of watching a number move. If I check it occasionally, use changes as prompts for sensible investigation, and keep broader financial tasks in the tools built for them, it earns a permanent place on my phone. If I want budgeting, banking, investment management, or a complete credit-research workspace, I would choose additional or different tools rather than asking this app to do everything.
My final view is positive but measured. CreditWise is not a complete financial plan and should not be treated as a guaranteed lending forecast. It is a focused companion for people who want credit awareness to become a normal part of their routine. For that purpose, I would recommend keeping it installed—provided I use it calmly, periodically, and with the understanding that noticing a problem is only the first step toward resolving it.
In short, CreditWise from Capital One earns lasting space through low-effort awareness rather than a long list of extras. It is best for readers who want a simple credit check that can sit beside their existing financial tools. I would skip it only when my needs are broader than monitoring or when another service already gives me the same information in a routine I genuinely maintain.
CreditWise from Capital One FAQ
What is CreditWise from Capital One, and what does it do?
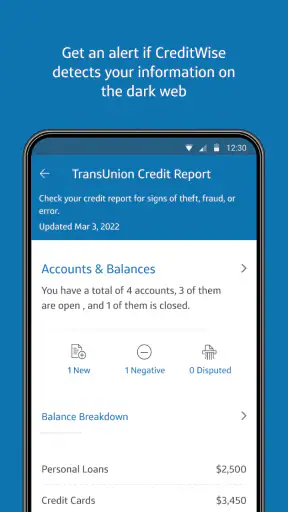
CreditWise from Capital One is a free credit-monitoring app designed to help users understand and track their credit profile. It typically provides access to a VantageScore 3.0 credit score, TransUnion credit-report information, score factors, and monitoring alerts. You do not need to be a Capital One banking customer to use the service, although availability and displayed information can vary by user and region.
Is CreditWise really free, or are there hidden charges?
CreditWise is generally offered at no cost, and checking your score through the app does not normally create a hard inquiry or lower your credit score. The service is intended as an educational and monitoring tool rather than a paid credit-repair product. However, users should remember that other Capital One products, third-party offers, or financial services promoted elsewhere may have separate terms, fees, eligibility requirements, or interest charges.
Will using CreditWise affect my credit score?
Using CreditWise to view your score, report information, or monitoring alerts is considered a soft inquiry and should not hurt your credit score. This makes it useful for checking your credit regularly without the concern associated with applying for a loan or credit card. Nevertheless, applying for products through links or offers outside the monitoring feature could result in a separate hard inquiry, depending on the provider and application process.
How accurate and up to date is the credit information in CreditWise?
CreditWise obtains information from TransUnion, but the timing of updates depends on when lenders and other data providers report changes. Your score may therefore differ from scores shown by another bureau, lender, or financial app because different scoring models and report data can be used. The app is helpful for tracking trends and spotting possible issues, but it should not be treated as a guaranteed lending decision or a complete real-time credit record.
What privacy and security considerations should I know before downloading CreditWise?
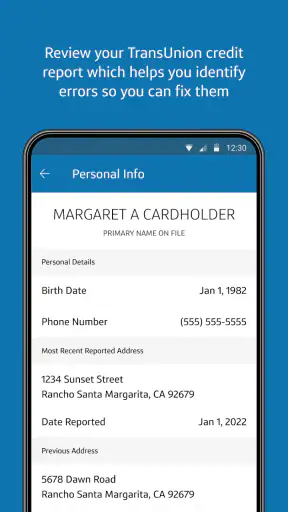
CreditWise requires personal information to identify you and retrieve your credit data, so users should review the app’s privacy policy, permissions, and account-security options before signing up. Use a strong, unique password and enable available security protections such as biometric login or multifactor authentication. The app can help identify suspicious changes, but it cannot prevent every form of identity theft, and users should report suspected fraud directly to the relevant financial institutions and authorities.













